A moderate moat, not a wide one: the bank licence is the hardest layer, and the advantage is mainly cost and scale rather than a dominant position
Read more
The figures to watch are loan defaults, member growth and net interest margin.
Proprietary data flywheel · Neutral. In June, selling members more products was still a work in progress. In Q3 members held 1.56 products each, up from 1.47 a year earlier, and 51% of new products went to existing members, though crypto accounts that earn little pad the count.
Regulation & licences · Strong. The 2022 bank charter lets it fund loans with deposits, which cost less than borrowing from other lenders, and keep those loans on its books. In October the charter let SoFi launch tokenized deposits for consumers, which SoFi calls a first for a national bank.
Physical assets & network · Narrow. No physical assets to speak of. Its network is the banking technology it sells to other fintechs (Galileo, Technisys, now Peach), running about 140 million accounts: a second, narrower advantage. That business's revenue fell 24% in Q3 after a large client left.
Trust & brand · Neutral. Stronger than online-only fintechs, weaker than the big banks: it lacks their decades of trust, and financial products are so alike that customers switch for a slightly better rate.
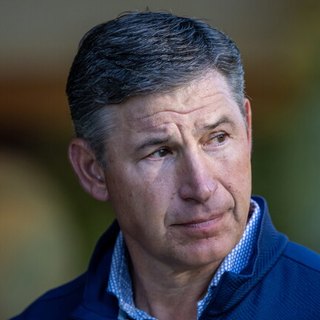
Owner-operator · Neutral. Anthony Noto, CEO since 2018, is not a founder, but he bought like an owner when it counted: he and his wife have bought about 2.9 million SoFi shares on the market since 2021, most of them at about $4.40 in December 2022. He has not sold on the market, but in 2024 and 2025 he raised $46.6 million by agreeing to sell 3.5 million shares later. A West Point graduate, he co-ran technology, media and telecom banking at Goldman Sachs, was the NFL's finance chief and Twitter's CFO. Next test: no new funding in 2027, as promised.